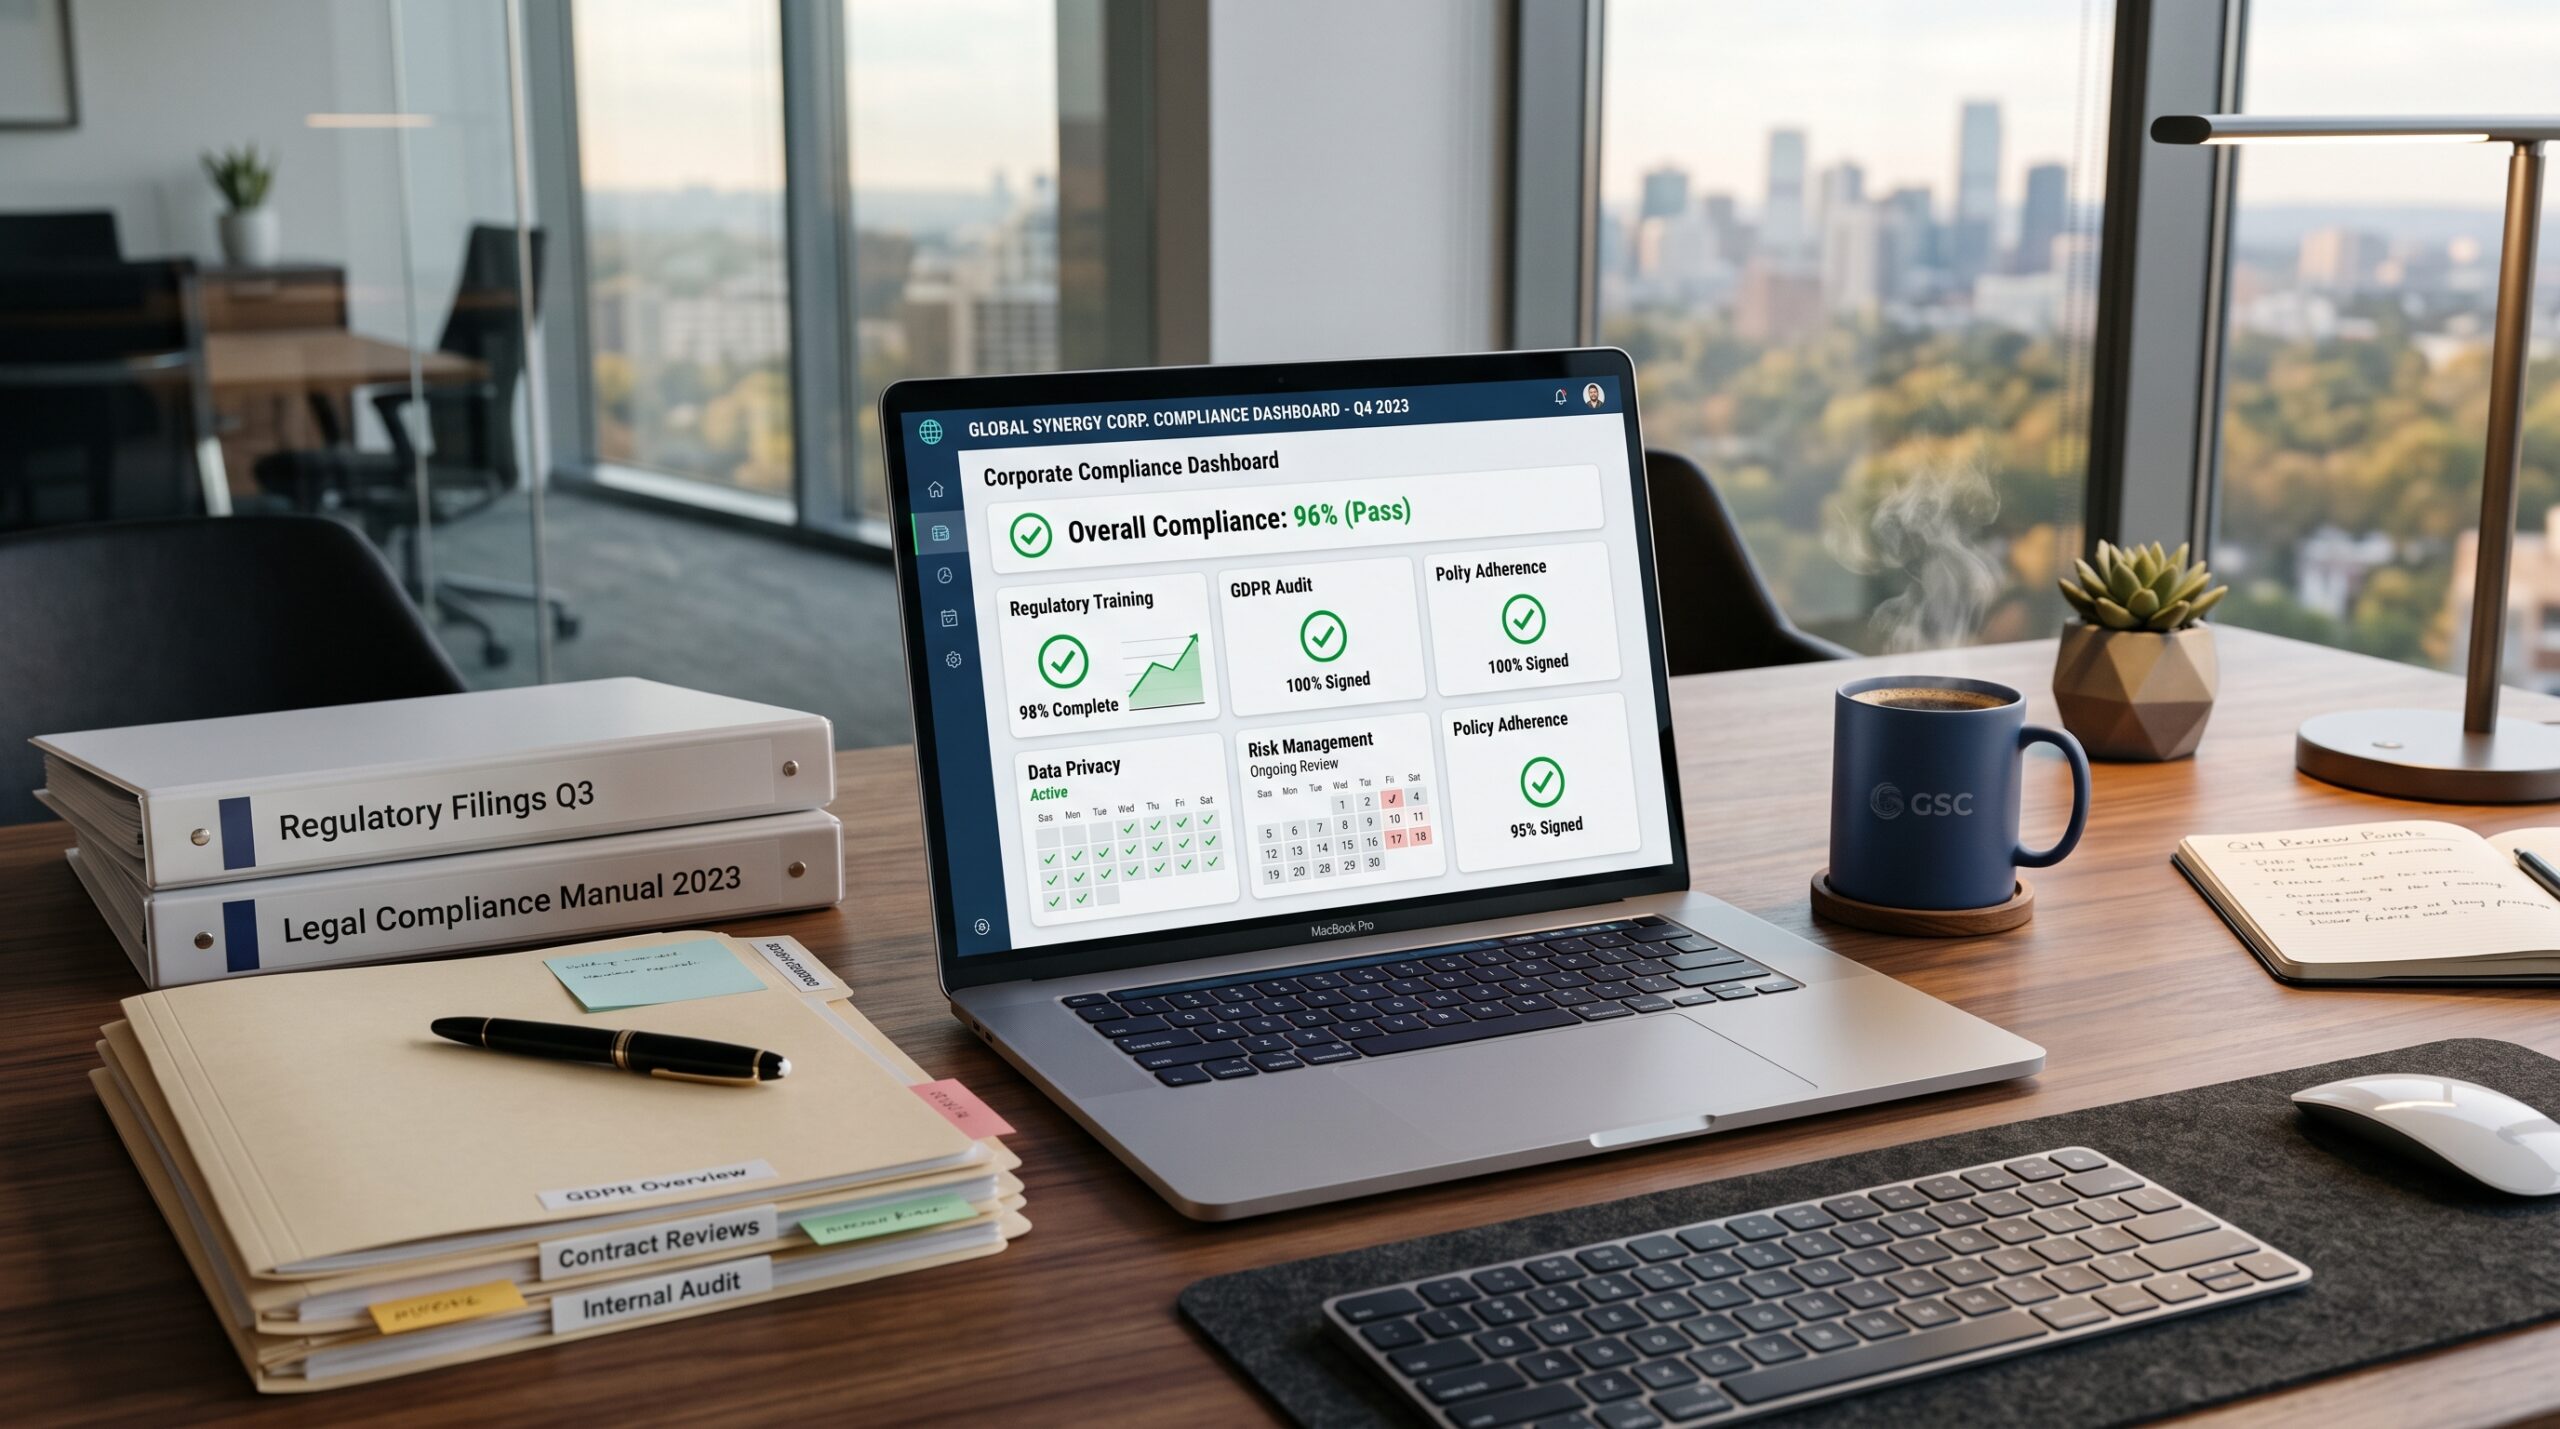
The adrenaline rush of launching a startup usually masks the quiet administrative machinery humming beneath the surface. You spend your early months closing clients, writing code, and refining your value proposition. Then, unannounced, a penalty notice from the state registry or tax authority arrives in your inbox.
Ignoring corporate compliance is the fastest way to turn your hard-earned venture into a regulatory liability.
Many founders assume that once incorporation paperwork clears, their legal obligations evaporate for the foreseeable future. That misconception can lead to administrative dissolution, lost liability shields, and heavy fines. Maintaining active corporate standing requires discipline, precision, and an ongoing calendar of mandatory filings. This guide explores the core annual compliance requirements every startup founder must manage to stay protected.
The Perils of Lapsing on State Annual Reports
Keeping Your Corporate Charter Alive
Every corporation or LLC must file an annual report or periodic statement with its state of incorporation (and in every foreign state where it is registered to do business). This filing is not an optional suggestion; it is the state’s primary method for tracking changes to your management team, principal address, and registered agent.
Failing to submit this document on time triggers administrative penalties, late fees, and eventual revocation of your corporate charter.
The Loss of the Liability Shield
When a state administratively dissolves your company for missing an annual report, the consequences go deeper than a simple fine.
-
Piercing the Veil: Operating a business whose corporate status has been revoked can strip away your limited liability protection, exposing your personal bank accounts to company lawsuits.
-
Impeding Financing: Investors and commercial banks routinely pull certificates of good standing during due diligence. A delinquent compliance record will freeze fundraising negotiations instantly.
Expert Insight: Set automated calendar reminders 60 days before your state’s annual report deadline. Never wait until the final week, as technical glitches on state web portals can cause you to miss the cutoff.
Maintaining Accurate Minutes and Corporate Resolutions
Documenting High-Level Decisions
Corporate governance requires more than just informal chats over Slack or coffee. State laws and corporate bylaws mandate that corporations and multi-member LLCs hold regular meetings and keep formal written records of major decisions.
Whether you are approving equity grants, signing commercial leases, or authorizing a bridge loan, these actions must be memorialized.
Creating an Audit-Ready Paper Trail
When legal disputes arise or investors audit your books, a missing paper trail can invalidate crucial structural changes.
-
Annual General Meetings (AGMs): Formally document your annual meetings to review financial performance, elect directors, and ratify board decisions.
-
Unanimous Written Consents: When formal meetings are impractical, use signed written consents to capture decisions legally without gathering the entire board in one room.
Tax Filings, Information Returns, and Bookkeeping Integration
Aligning Financials with Legal Obligations
Corporate compliance and tax compliance are permanently joined at the hip. Falling behind on your bookkeeping makes accurate tax filing impossible, which in turn flags your business for federal and state audits.
You must maintain separate business bank accounts and reconcile ledgers monthly rather than scrambling to reconstruct twelve months of receipts at year-end.
Navigating Multi-Tier Tax Duties
Meeting your fiscal requirements extends far beyond standard corporate income tax returns.
-
Information Returns: Entities like partnerships and S-corporations must file informational returns detailing shareholder allocations even if corporate income tax is passed through.
-
Sales and Payroll Tax Compliance: If you sell taxable goods or employ staff, you must collect, report, and remit local sales and payroll taxes on strict monthly or quarterly schedules.
Expert Insight: Invest in reputable cloud accounting software from day one. Clean, automated books cut your year-end accountant fees in half and ensure you never miss an estimated tax payment window.
Managing Registered Agent and Office Updates
The Official Gateway for Legal Service
Your registered agent is the designated individual or entity authorized to accept official legal notices, lawsuits, and state correspondence on behalf of your startup.
If your registered agent moves, changes their email, or resigns without a prompt replacement, you risk missing a lawsuit deadline and suffering a default judgment without ever knowing you were sued.
Keeping State Records Current
Whenever your operational footprint evolves, your official state filings must reflect those changes immediately.
-
Office Relocation: Moving your headquarters across city or county lines often requires filing an amendment to your articles of organization or incorporation.
-
Foreign Qualification: If your startup begins hiring remote employees or opening physical offices in a new state, you must register as a foreign entity in that jurisdiction.
Building a Proactive Compliance Calendar
Transitioning from Reactive Scrambling to Routine
Compliance failures rarely stem from malicious intent; they happen because founders are overwhelmed by product development and miss unpublicized deadlines.
The most successful entrepreneurs treat regulatory upkeep like software maintenance—scheduled, predictable, and automated wherever possible.
Establishing Internal Checkpoints
Designing a bulletproof workflow protects your business from administrative oversight.
-
Assign Ownership: Designate a specific team member or retain an outside corporate secretary service to oversee regulatory calendars.
-
Periodic Audits: Conduct a quarterly compliance review to verify that business licenses, intellectual property filings, and state registrations remain active and fully up to date.
FAQ
1. What happens if I miss my state’s annual report deadline?
Missing your state’s annual report deadline typically results in late fees and penalties. If left unaddressed for months, the state can administratively dissolve your company, stripping away your liability shield and making it illegal to conduct business under that corporate name.
2. Do single-member LLCs need to keep meeting minutes?
While single-member LLCs face lighter governance burdens than corporations, maintaining written resolutions for major financial transactions, asset purchases, or bank account changes is vital to prove corporate separation and protect your personal liability shield.
3. What is a registered agent and why is one mandatory?
A registered agent is an individual or corporate service authorized to receive legal notices and government correspondence on behalf of your business. States mandate a registered agent to ensure there is always a reliable, fixed point of contact available during standard business hours for service of process.
4. How do I know if my startup needs to register in multiple states?
Generally, if your startup establishes a physical office, hires W-2 employees, or maintains significant inventory in a state outside your home jurisdiction, you are “doing business” there and must file a foreign qualification in that state.
5. Can I use accounting software to handle my annual compliance filings?
While cloud accounting software excels at bookkeeping and financial reporting, it rarely handles state-specific annual reports or corporate secretarial filings automatically. You will still need to track state deadlines manually, use a dedicated compliance automation platform, or partner with a corporate attorney.
Conclusion
Corporate compliance is not just a collection of tedious bureaucratic chores; it is the structural armor that safeguards your startup’s legal standing and investor appeal. By treating annual reports, tax filings, and governance record-keeping as core operational priorities, you eliminate hidden liabilities and build a resilient foundation for long-term growth. Audit your compliance calendar today and ensure your business stays protected.
Leave a Reply